Quarterly Tax Updates | September 2026
RRH Quarterly Tax Updates provides businesses, finance professionals and tax practitioners with timely insights into key developments in Bangladesh taxation, including income tax, VAT, customs, regulatory compliance and emerging tax policy. Designed to help organisations understand regulatory changes, manage tax risks and make informed commercial decisions, the publication reflects Rahman Rahman Huq (RRH)'s more than 60-year history of serving businesses in Bangladesh. As a trusted and leading tax advisor and former first Big 4/KPMG member firm, RRH combines deep market experience with practical, commercially informed advice across tax advisory, due diligence, M&A, tax audits, appeals and dispute management, reinforcing its commitment to service excellence and trusted professional support.
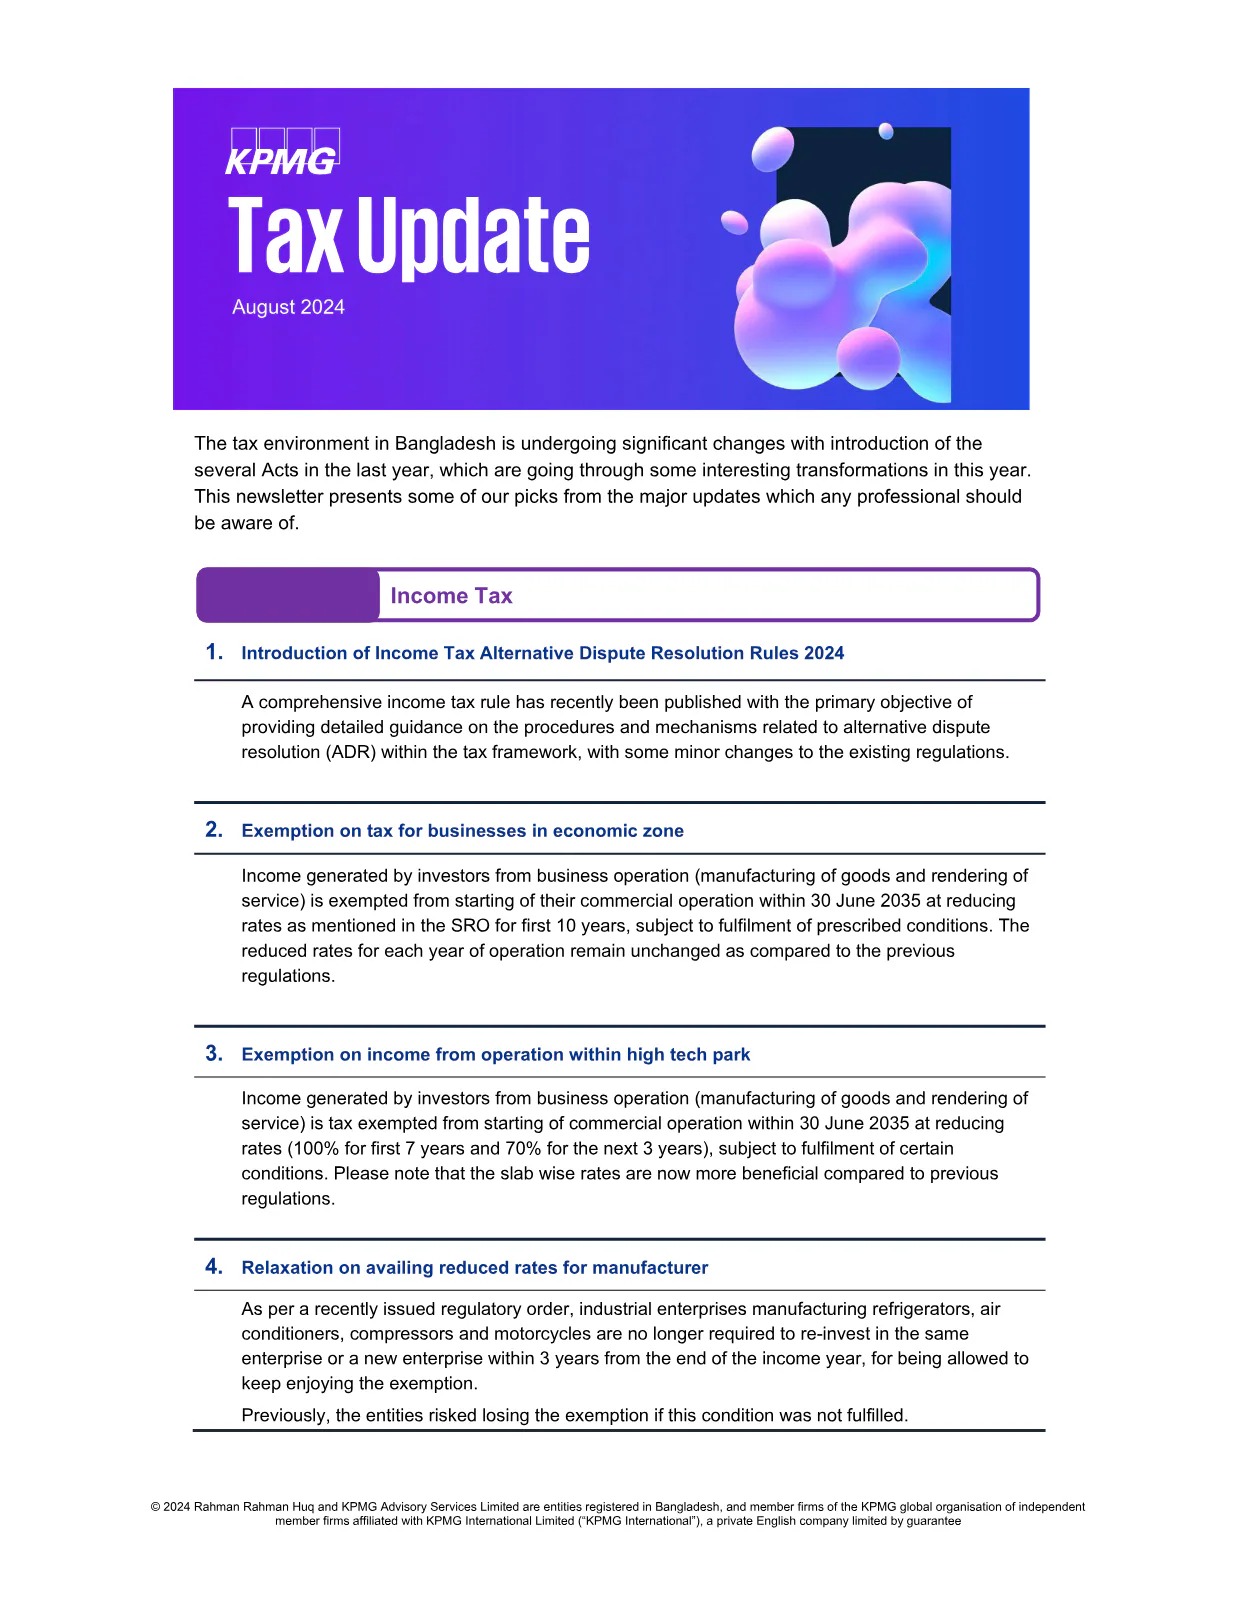
This newsletter covers income tax, VAT and customs changes in Bangladesh up to August 2024, following the Finance Act 2024 and a series of new rules and SROs.
Income tax: the Income Tax Alternative Dispute Resolution Rules 2024 were published. Investors in economic zones and hi-tech parks starting commercial operation by 30 June 2035 receive reducing-rate exemptions; for hi-tech parks this is 100% for seven years and 70% for the next three. Manufacturers of refrigerators, air conditioners, compressors and motorcycles no longer need to reinvest within three years to keep reduced rates. Under amendments to the TDS Rules 2024, deduction for gas distribution entities is reduced to 2% and the rate on fruit suppliers rises from 1% to 2%. The update also covers environmental surcharge on multiple vehicles, the Income Tax Paripatra 2024-25, and TDS on land leases, which is 50% higher without proof of submission of return (PSR).
VAT and customs: new rules on expedited shipments, authorised economic operators, general bonds, warehouse licensing (BDT 100,000 fee, three-year validity), electronic filing and customs guarantees; revised duty concessions for local manufacture of mobile phones, electric motors, motorcycles, ATMs, generators and LED lamps; narrower exemptions on vehicles imported by EZ and hi-tech park units; and a BDT 100 million turnover threshold for withholding entities.